Your Guide To all things accounting and finance
Ledger Labs' Glossary
Real businesses. Real results. Hear firsthand how Ledger Labs’ products, solutions, and expert strategies are helping companies grow faster, operate smarter, and plan for the future with confidence.
2,246+
Happy Clients
12 +
Years in industry
150 +
Strong team
Accounting Glossary
Ledger labs, provide you with an easy A-Z of accounting terms.
- 409A Valuation
- An independent appraisal of a private company’s common stock fair market value, required by IRS Section 409A before issuing stock options. Typically refreshed annually or after a material event.
- Accounts Payable Turnover
- A ratio measuring how many times a business pays off its suppliers in a period. Low turnover can signal cash strain; very high may mean you’re paying faster than needed.
- Accounts Receivable Aging
- A report grouping unpaid customer invoices by how long they’ve been outstanding (0-30, 31-60, 61-90, 90+ days). The first place to look when cash is tight but revenue looks fine.
- Accounts Receivable Turnover
- A ratio showing how many times a business collects its average receivables balance in a period. A falling ratio usually precedes a cash flow problem by a quarter.
- Accrual Accounting
- A method recording revenue when earned and expenses when incurred, regardless of when cash moves. Required under GAAP and expected by lenders and acquirers above roughly $5M in revenue.
- Accrued Expenses
- Costs a business has incurred but not yet paid or been invoiced for, recorded as liabilities. Common examples are wages, interest and utilities at period end.
- Amortization
- The systematic write-off of an intangible asset’s cost over its useful life, or the gradual repayment of loan principal. The intangible-asset equivalent of depreciation.
- Analytic Accounting
- A cost-tracking layer that tags transactions to projects, departments or cost centers independently of the chart of accounts. Odoo’s approach to management reporting.
- ASC 842 Lease Accounting
- The US GAAP standard requiring most leases – operating and finance – to appear on the balance sheet as a right-of-use asset and lease liability.
- Bank Reconciliation
- The process of matching a company’s internal cash records to its bank statement and resolving differences. The single most common source of unreliable SMB financials.
- Bill of Materials (BOM)
- A structured list of every raw material, component and sub-assembly needed to manufacture one unit of a finished product, with quantities. The foundation of accurate manufacturing costing.
- Bonus Depreciation
- A tax provision allowing an immediate deduction of a set percentage of qualifying asset cost in the year placed in service, rather than depreciating over its life.
- Break-Even Point
- The sales level at which total revenue equals total costs and profit is zero. Calculated as fixed costs divided by contribution margin per unit.
- Budget Variance
- The difference between a budgeted figure and the actual result, expressed in dollars or percent. Favorable or unfavorable depending on direction and line item.
- Burn Rate
- The rate at which a business consumes cash reserves, usually stated monthly. Gross burn is total cash out; net burn is cash out less cash in.
- Business Valuation
- The process of determining a company’s economic value, using income, market or asset-based approaches. Required for sale, fundraising, partner buyouts and estate planning.
- Cap Table
- A record of a company’s ownership – who holds equity, options, warrants and convertible instruments, and at what percentages. Errors here surface expensively during diligence.
- Cash Basis Accounting
- A method recording revenue when cash is received and expenses when paid. Simple and permitted for smaller businesses, but it obscures true period performance.
- Cash Conversion Cycle
- The number of days between paying for inventory and collecting cash from its sale. Calculated as DIO + DSO – DPO.
- Cash Flow Forecasting
- Projecting future cash inflows and outflows over a defined horizon, typically 13 weeks for operations or 12 months for planning.
- Cash Runway
- How many months a business can operate before cash reaches zero at the current net burn rate.
- Chargeback
- A forced reversal of a card transaction initiated by the cardholder’s bank. For sellers, chargebacks hit revenue, fees and inventory simultaneously and need dedicated reconciliation treatment.
- Chart of Accounts
- The organized list of every account used to record transactions in the general ledger, grouped by assets, liabilities, equity, revenue and expenses. Its design determines what your reports can tell you.
- Class Tracking
- A QuickBooks feature assigning transactions to a segment – location, department, product line – so financials can be reported by that segment without separate accounts.
- Cloud ERP
- An enterprise resource planning system hosted and maintained by the vendor and accessed over the internet, rather than installed on a company’s own servers.
- Contribution Margin
- Revenue less variable costs, showing how much each sale contributes toward fixed costs and profit. Expressed per unit, per product line, or as a percentage.
- Cost of Goods Sold (COGS)
- The direct costs of producing or acquiring the goods a business sold in a period – materials, direct labor and inbound freight. Excludes overhead and selling costs.
- Current Ratio
- Current assets divided by current liabilities, measuring short-term ability to cover obligations. Below 1.0 signals liquidity risk.
- Cycle Counting
- Counting a subset of inventory on a rolling schedule instead of shutting down for a full physical count. Keeps inventory accurate without halting operations.
- Days Payable Outstanding (DPO)
- The average number of days a business takes to pay its suppliers. Extending DPO frees cash but can strain vendor relationships.
- Days Sales Outstanding (DSO)
- The average number of days to collect payment after a sale. Rising DSO is an early warning of collection or customer-quality problems.
- Debt-to-Equity Ratio
- Total liabilities divided by shareholders’ equity, measuring how much of the business is financed by debt versus owner capital. A core lender covenant.
- Deferred Revenu
- Cash collected for goods or services not yet delivered, recorded as a liability until earned. Misclassifying it overstates revenue and distorts valuation.
- Dimensional Accounting
- Tagging transactions with attributes – department, location, project, customer – so one chart of accounts can produce many reporting views. Called Dimensions in Sage Intacct and Business Central, Classes in QuickBooks, Tracking Categories in Xero.
- EBITDA
- Earnings before interest, taxes, depreciation and amortization – a proxy for operating cash generation. The headline figure in most SMB acquisition conversations.
- EBITDA Multiple
- The ratio of enterprise value to EBITDA, used to price a business. Multiples vary by sector, size, growth and the quality of the financials behind the number.
- Economic Nexus
- A sales tax obligation triggered by exceeding a state’s revenue or transaction threshold, without any physical presence there. Established by South Dakota v. Wayfair.
- Economic Order Quantity (EOQ)
- The order size that minimizes total inventory cost by balancing ordering costs against holding costs.
- Electronic Data Interchange (EDI)
- A standardized format for exchanging business documents – purchase orders, invoices, shipping notices – between trading partners’ systems without manual entry. Mandatory for most big-box retail vendors.
- ERP (Enterprise Resource Planning)
- An integrated software system running accounting, inventory, purchasing, operations and reporting on one shared database, replacing disconnected tools.
- ERP Data Migration
- Moving master data, open transactions and historical balances from a legacy system into a new ERP. The step that most often determines whether an implementation succeeds.
- ERP Implementation
- The full project of configuring, migrating to and going live on an ERP system – covering design, data, testing, training and cutover.
- Estimated Tax Payments
- Quarterly prepayments of income tax made by businesses and individuals whose tax isn’t fully withheld. Underpayment triggers IRS penalties even if the annual return is filed on time.
- FIFO
- First In, First Out – an inventory costing method assuming the oldest units are sold first. In rising-cost environments it reports higher profit and higher ending inventory than LIFO.
- Financial Modeling
- Building a structured projection of a company’s financial performance, linking the income statement, balance sheet and cash flow statement under defined assumptions.
- Financial Statement Audit
- An independent examination of financial statements by a licensed firm, resulting in a formal opinion on whether they fairly present the company’s position under GAAP.
- Fixed Asset Register
- A detailed schedule of a company’s fixed assets, with acquisition cost, in-service date, useful life, accumulated depreciation and net book value.
- Form 1099-NEC
- The IRS form reporting non-employee compensation of $600 or more paid to contractors during the year. Due to recipients and the IRS by January 31.
- Form 1120-S
- The US income tax return filed by S corporations, reporting income, deductions and credits that pass through to shareholders via Schedule K-1.
- Form W-9
- The IRS form used to collect a vendor’s or contractor’s legal name, entity type and taxpayer identification number. Collected before payment, not at year end.
- Fractional CFO
- A senior finance executive engaged part-time or on retainer, providing strategic financial leadership without a full-time hire. Typically engaged by businesses past roughly $2M in revenue.
- Free Cash Flow
- Operating cash flow less capital expenditures – the cash genuinely available to repay debt, reinvest or distribute to owners.
- General Ledger Integration
- Connecting an operational system – payroll, POS, ecommerce platform, inventory tool – so its transactions post automatically into the accounting general ledger.
- Gross Margin
- Revenue less COGS, expressed in dollars or as a percentage of revenue. The clearest single measure of whether a product or business model works.
- Gross Merchandise Value (GMV)
- The total value of goods sold through a platform or channel over a period, before returns, discounts and fees. Not revenue, and frequently confused with it.
- Hard Close
- A month-end close performed with full year-end rigor – all reconciliations and adjustments completed. Contrasted with a soft close, which skips steps for speed.
- Headcount Planning
- Forecasting staffing levels and fully loaded employee costs by role and period, tied to the financial plan. Usually the largest controllable line in an operating budget.
- Hedge Accounting
- An accounting treatment aligning the timing of gains and losses on a hedging instrument with those on the item it hedges, reducing earnings volatility.
- High-Low Method
- A cost estimation technique separating fixed and variable components by comparing costs at the highest and lowest activity levels in a period.
- Historical Cost
- The GAAP principle recording assets at original purchase price rather than current market value, adjusted only for depreciation or impairment.
- Holdback
- A portion of purchase price withheld at closing and released later, protecting the buyer against post-close claims or performance shortfalls.
- Holding Company
- A parent entity whose primary purpose is owning controlling interests in other companies rather than producing goods or services itself.
- Horizontal Analysis
- Comparing a financial statement line item across multiple periods to identify trends, expressed in dollar and percentage change.
- Human Capital Management (HCM)
- The ERP module handling payroll, benefits, time tracking and workforce records, integrated with the general ledger.
- Hurdle Rate
- The minimum rate of return a project must clear to justify investment. Usually set at or above the company’s weighted average cost of capital.
- Intercompany Eliminations
- Removing transactions and balances between related entities during consolidation so the group’s financials aren’t inflated by internal activity.
- Internal Controls
- The policies and procedures safeguarding assets, ensuring accurate records and preventing fraud – approval limits, reconciliations, segregation of duties.
- Inventory Shrinkage
- The gap between recorded inventory and physical inventory on hand, caused by theft, damage, spoilage or clerical error.
- Inventory Turnover Ratio
- How many times inventory is sold and replaced in a period, calculated as COGS divided by average inventory. Low turnover ties up cash in stock.
- Job Costing
- Assigning materials, labor and overhead to a specific job, project or batch to determine its individual profitability.
- Journal Entry
- A record of a transaction in the general ledger, with equal debits and credits, a date and a description. The atomic unit of double-entry bookkeeping.
- Kaizen Costing
- A continuous-improvement approach targeting incremental cost reductions during production rather than at the design stage.
- Kanban
- A visual scheduling system triggering replenishment when stock hits a set level, pulling production or purchasing from actual demand rather than forecast.
- Key Audit Matter (KAM)
- A matter the auditor judges most significant to the audit, disclosed in the audit report along with how it was addressed.
- Key Performance Indicator (KPI)
- A quantifiable measure tracked to evaluate progress against a business objective. Finance KPIs typically cover liquidity, profitability, efficiency and growth.
- Key Person Insurance
- A policy owned by the business on an owner or critical employee, paying out to cover the financial disruption of their loss. Often required by lenders and in buy-sell agreements.
- Kiting
- A fraud scheme exploiting the float between banks by writing cheques against uncollected funds to conceal a cash shortfall.
- Knowledge Process Outsourcing (KPO)
- Outsourcing judgement-based work such as accounting, analysis and financial reporting, as distinct from routine transaction processing.
- Landed Cost
- The total cost of getting a product to your warehouse – unit price plus freight, duties, insurance, customs and handling. Ignoring it systematically overstates gross margin.
- LIFO
- Last In, First Out – an inventory costing method assuming the newest units are sold first. Permitted under US GAAP but prohibited under IFRS.
- Marketplace Facilitator Tax
- State laws making the marketplace – Amazon, Walmart, eBay – responsible for collecting and remitting sales tax on seller transactions, rather than the seller.
- Material Requirements Planning (MRP)
- A system calculating what materials to purchase or produce, in what quantity and by when, based on demand forecasts, BOMs and current inventory.
- Month-End Close
- The recurring process of reconciling accounts, posting accruals and adjustments, and finalizing financial statements for a completed month.
- Multi-Book Accounting
- Maintaining parallel sets of books for the same transactions under different accounting standards or reporting bases – GAAP, IFRS, tax or management.
- Multi-Entity Consolidation
- Combining the financial results of multiple legal entities into a single set of group statements, with intercompany activity eliminated.
- Multi-Warehouse Inventory
- Tracking stock levels, costs and movements across multiple physical locations within one inventory system, including transfers between them.
- Net Profit Margin
- Net income as a percentage of revenue – what’s left after every cost, including interest and taxes.
- Obsolete Inventory
- Stock that can no longer be sold at normal price because of age, damage or lost demand. Must be written down, and the write-down hits gross margin.
- Operating Expenses (OpEx)
- The costs of running the business that aren’t direct product costs – rent, salaries, software, marketing, insurance.
- Overhead Absorption Rate
- The rate at which indirect manufacturing costs are applied to units produced, usually per labor hour, machine hour or unit.
- Prepaid Expenses
- Payments made in advance for goods or services to be received later, recorded as assets and expensed as consumed. Insurance and annual software contracts are typical.
- Purchase Order (PO)
- A buyer-issued document authorizing a purchase, specifying items, quantities, prices and terms. Becomes a binding commitment once the seller accepts it.
- Purchase Price Variance (PPV)
- The difference between the standard cost of a purchased item and the price actually paid. Tracks procurement performance and flags costing errors.
- QBI Deduction (Section 199A)
- A deduction of up to 20% of qualified business income for owners of pass-through entities, subject to income thresholds and business-type limits.
- Quality of Earnings (QoE)
- An independent analysis assessing how sustainable and accurately stated a company’s earnings are, separating recurring operating performance from one-offs. Standard in acquisition diligence.
- R&D Tax Credit
- A federal credit for qualified research expenses, available to businesses developing or improving products, processes or software. Can offset payroll tax for eligible small businesses.
- Reorder Point
- The inventory level triggering a new purchase order, calculated from lead time demand plus safety stock.
- Retained Earnings
- Cumulative net income a business has kept rather than distributed to owners, carried on the balance sheet within equity.
- Return on Equity (ROE)
- Net income divided by shareholders’ equity, measuring how efficiently owner capital generates profit.
- Revenue Recognition (ASC 606)
- The US GAAP standard defining when and how much revenue to record, using a five-step model built around the transfer of control to the customer.
- Rolling Forecast
- A forecast continuously extended as periods close, always covering a fixed horizon ahead – typically 12 or 18 months – rather than stopping at fiscal year end.
- Safe Harbor Rule
Concept in statutes and regulations whereby a person who meets listed requirements will be preserved from adverse legal action. Frequently, safe harbors are used where a legal requirement is somewhat ambiguous and carries a risk of punishment for an unintended violation.
- Sarbanes Oxley Act
An act designed to improve quality and transparency in financial reporting and independent audits and accounting services for public companies, to create a Public Company Accounting Oversight Board, to enhance the standard-setting process for accounting practices, to strengthen the independence of firms that audit public companies, to increase corporate responsibility and the usefulness of corporate financial disclosure, to protect the objectivity and independence of securities analysts, to improve Securities and Exchange Commission resources and oversight and for other purposes.
- SEC Filings
Financial and informational disclosures required by the SEC in order to comply with certain sections of the Securities Act of 1933 and the Securities and Exchange Act of 1934. Some of the more common filings that publicly owned companies must submit are the form 10-K, form 10-Q and form 8-K.
- Security
Any kind of transferable certificate of ownership including equity securities and debt securities.
- Short Sale
Sale of an item before it is purchased. A person entering into a short sale believes the price of the item will decline between the date of the short sale and the date he or she must purchase the item to deliver the item under the terms of the short sale.
- Special Report
Special report is a term applied to auditors’ reports issued in connection with various types of financial presentations, including financial statements that are prepared in conformity with a comprehensive basis of accounting other than generally accepted accounting principles; specified elements, accounts or items of a financial statement. Compliance with aspects of contractual agreements or regulatory requirements related to audited financial statements. Financial presentations to comply with contractual agreements or regulatory provisions. Financial information presented in prescribed forms or schedules that require a prescribed form of auditors’ reports.
- Spread
Difference between two prices, usually a buying and selling price.
- Start-up Costs
(1) Costs, excluding acquisition costs, incurred to bring a new unit into production. (2) Costs incurred to begin a business.
- Statement of Cash Flows
A statement of cash flows is one of the basic financial statements that is required as part of a complete set of financial statements prepared in conformity with generally accepted accounting principles. It categorizes net cash provided or used during a period as operating, investing and financing activities, and reconciles beginning and ending cash and cash equivalents.
- Stock Option
Right to purchase or sell a specified number of shares of stock at specified prices and times.
- Tangible Asset
Assets having a physical existence, such as cash, land, buildings, machinery, or claims on property, investments, or goods in process. (See intangible assets.)
- Tax
Charge levied by a governmental unit on income, consumption, wealth, or other basis.
- Taxation
Process of instituting a charge against a legal entity’s person, property or activity for the support of government. (For example, income taxes, sales taxes, duties and levies.) [See Tax]
- Trust
Ancient legal practice where one person (the grantor) transfers the legal title to an asset, called the principle or corpus, to another person (the trustee), with specific instructions about how the corpus is to be managed and disposed.
- Ultimate Beneficial Owner (UBO)
- Under UAE Cabinet Resolution No. 58 of 2020, companies must maintain a register identifying individuals who ultimately own or control 25% or more of the company, a disclosure requirement specific to UAE corporate compliance and accounting records.
- Utilization Rate
- Utilization rate measures how effectively a company uses its available resources, such as labour hours or machinery capacity. It is calculated by comparing actual productive time to total available time. Higher utilisation indicates operational efficiency, while low rates may signal underperformance, excess capacity, or poor resource planning.
- Usury
- Usury refers to the practice of charging excessively high interest rates on loans beyond legally permitted limits. While primarily a legal concept, it has accounting implications in interest expense recognition and financial disclosure. Companies must ensure lending or borrowing arrangements comply with regulatory standards to avoid penalties and reputational damage.
- Upstream Transaction
- An upstream transaction occurs when a subsidiary sells goods or services to its parent company. In consolidated financial statements, unrealised profits from such transactions must be eliminated to avoid overstating group income. Proper treatment ensures the consolidated accounts reflect only profits earned from external parties.
- Understated
- Understated describes a situation where an asset, income, or equity figure is recorded at a value lower than its actual amount. This may occur due to errors, omissions, or conservative accounting practices. Understatement can mislead stakeholders about financial strength and profitability, making accurate adjustments essential for fair financial reporting.
- Underlying Profit
- Underlying profit refers to a company’s earnings after removing one-time, non-recurring, or exceptional items that may distort performance. It provides a clearer picture of core operational results by excluding unusual gains or losses. Analysts use underlying profit to assess sustainable profitability and compare financial performance consistently across reporting periods.
- Unit Trust
- A unit trust is a collective investment scheme where investors pool funds to invest in diversified assets such as stocks, bonds, or property. Each investor holds units representing their share of the portfolio. It offers professional management and risk diversification.
- Underwriting Commission
- Underwriting commission is the fee paid to underwriters for assuming the risk of buying and reselling securities or insurance policies. In accounting, it is recorded as an expense by the issuing company and forms part of the cost of raising capital.
- Unearned Discount
- An unearned discount is the portion of a financial discount received before it is actually earned, typically on prepaid expenses or early payments. It appears as a liability until the related time or condition is fulfilled, after which it is recognised as income.
- Unqualified Opinion
- An unqualified opinion is the most favourable audit opinion, issued when an auditor concludes that the financial statements present a true and fair view in accordance with applicable accounting standards. It reflects sound accounting practices and strong internal controls.
- Unit-level Activity
- Unit-level activity refers to actions performed each time a single unit of product is produced. Examples include direct labour hours, machine operations, or material consumption. Tracking these activities helps determine variable costs and refine product pricing under activity-based costing.
- Under-absorption of Overheads
- Under-absorption of overheads happens when the allocated overheads to products or jobs are less than the actual overheads incurred. It indicates underestimation or inefficiency in cost allocation and may require adjusting future absorption rates for accuracy.
- Unfavourable Variance
- An unfavourable variance occurs when actual costs exceed budgeted or standard costs, or when actual revenue falls short of expectations. It signals inefficiencies or poor performance and helps management identify areas that need corrective action or cost control.
- Utility Expense
- Utility expense represents the cost of services such as electricity, water, gas, and internet used in business operations. It is classified as an operating expense and recognised on an accrual basis to reflect the period in which the utility is consumed.
- Uniform Costing
- Uniform costing is the practice of using a standardised cost accounting system across multiple firms in the same industry. It enables meaningful comparison of performance, cost control, and pricing strategies while promoting transparency and consistency in financial reporting.
- Useful Life
- Useful life is the estimated period over which an asset is expected to generate economic benefits for a business. It determines the depreciation or amortisation schedule applied to the asset. Estimating useful life accurately ensures realistic expense allocation, asset valuation, and compliance with accounting standards.
- Unpaid Expenses
- Unpaid expenses are costs incurred but not yet paid at the end of an accounting period. They are recorded as accrued liabilities and expensed on the income statement. Examples include unpaid salaries, utility bills, or interest. This ensures financial statements reflect all obligations, even if not yet settled.
- Unappropriated Retained Earnings
- Unappropriated retained earnings are the portion of net income not designated for a specific purpose (like dividends or reserves). They remain available for reinvestment or future distribution. Unlike appropriated earnings, these funds are unrestricted and can be used as management sees fit for business operations.
- Unit Cost
- Unit cost is the total expense incurred to produce, store, and sell one unit of product or service. It includes direct costs like materials and labour and may include allocated overhead. Understanding unit cost is essential for pricing, profitability analysis, and cost control in manufacturing and retail.
- Uncollectible Accounts
- Uncollectible accounts are receivables that are deemed unlikely to be recovered, often due to customer default or bankruptcy. These bad debts are written off from the books and may be estimated in advance through a provision for doubtful accounts. It ensures receivables aren’t overstated in financial reports.
- Unsecured Loan
- An unsecured loan is a loan that isn’t backed by collateral. Lenders rely on the borrower’s creditworthiness and financial stability. Because of higher risk, unsecured loans often carry higher interest rates. Examples include credit cards, personal loans, and some types of corporate financing.
- Unrealised Loss
- An unrealised loss occurs when the value of an asset drops below its purchase price, but it hasn’t been sold. Like unrealised gains, these losses are not final until the asset is disposed of. They may still impact financial reporting, depending on the accounting standards used.
- Unrealised Gain
- An unrealised gain is the increase in value of an asset that hasn’t yet been sold. It reflects a paper profit, not actual cash flow. For example, stocks that have risen in value but are still held are considered unrealised gains until they are sold and the gain is realised.
- Unearned Revenue
- Unearned revenue is money received before a product is delivered or a service is provided. It’s recorded as a liability on the balance sheet because the business still owes the service or goods. As the obligation is fulfilled, it is gradually recognised as earned revenue on the income statement.
- Valuation
Process of determining the worth of a company’s assets.
- Variance
Deviation or difference between an estimated value and the actual value.
- Venture Capital
Investment company whose primary objective is capital growth. New assets invested largely in companies that are developing new ideas, products, or processes.
- Volunteer Income Tax Assistance
(VITA) IRS program designed to help low and moderate-income taxpayers complete their annual tax returns at no cost.
- Withholding
Amount withheld or deducted from employee salaries by the employer and paid by the employer, for the employee, to the proper authority.
- Working Capital
Excess of current assets over current liabilities.
- X-Rate (Exhchange Rate)
- X-rate refers to the exchange rate applied when converting financial statements or transactions denominated in foreign currency. Accurate application ensures proper translation of revenues, expenses, assets, and liabilities. Variations in the X-rate can create translation differences that impact consolidated financial results and equity balances.
- X-Working Capital Adjustment
- X-working capital adjustment refers to a negotiated modification in merger or acquisition agreements that reconciles the target company’s actual working capital against an agreed benchmark at closing. If working capital differs from the target level, the purchase price is adjusted accordingly. This mechanism protects buyers and sellers from unexpected liquidity shifts before deal completion.
- Xerta
- Xerta refers to Xerta Payment Solutions, a platform facilitating digital transactions, particularly cross-border and business-to-business payments. In accounting, Xerta’s systems streamline receivables and payables, integrate with financial software, and ensure secure, compliant payment processing. This reduces reconciliation errors, improves efficiency, and helps businesses manage international payments and reporting with greater transparency and control.
- Xenocurrency
- Xenocurrency is any currency traded outside its home country’s borders. For example, US dollars held in European banks are xenocurrencies. In accounting and finance, xenocurrencies are important in international trade, foreign exchange markets, and global investments. They influence liquidity, interest rates, and exposure to currency risk for multinational firms and investors.
- XRT
- XRT, short for Extended Retail Transaction, refers to detailed records of point-of-sale (POS) activity in accounting and finance. It captures all transaction data, such as sales, discounts, returns, and payment methods, providing retailers and accountants with granular insights. This information supports inventory management, revenue tracking, audit trails, and accurate financial reporting.
- X- Mark Signature
- An X-mark signature is a simple cross or “X” used by individuals unable to write their full name, often on legal or financial documents. It serves as a legally recognised mark of consent or agreement, provided it is properly witnessed. In accounting, it validates records and authorisations where literacy or disability may be a concern.
- XML in Accounting Systems
- XML (eXtensible Markup Language) is used in accounting systems to structure and exchange financial data between applications. While not specific to accounting, XML plays a critical role in integrating ERP systems, automating reports, and enabling technologies like XBRL, bridging software platforms with real-time data exchange.
- X-Efficiency
- X-efficiency refers to a firm’s ability to use its resources effectively under conditions of competition. Though originally an economic concept, it’s relevant in managerial accounting and performance audits. It highlights the gap between optimal output and real-world inefficiencies caused by mismanagement, slack, or internal control weaknesses.
- X-Dividend Date
- The x-dividend date is the cutoff day when a stock begins trading without the value of its next dividend payment. Investors who purchase shares on or after the x-date won’t receive the upcoming dividend. It helps determine dividend eligibility and affects stock pricing near the payout period.
- XBRL (eXtensible Business Reporting Language)
- XBRL is a global XML-based standard used for the electronic communication of business and financial data. It enables consistent, automated reporting and easy comparison across organisations. Regulators, analysts, and software systems use XBRL to standardise financial statements, improving data accuracy, transparency, and speed of financial disclosures.
- Yellow Book
Written by the general accounting office, the yellow book sets forth standards to be followed in auditing the financial statements of entities that receive federal financial assistance. “Yellow Book” is the name given to “Government Auditing Standards” issued by the Comptroller General of the United States which contains standards for audits of government organizations, programs, activities and functions, and of government assistance received by contractors, non-profit organizations, and other non-government organizations.
- Yield
Return on an investment an investor receives from dividends or interest expressed as a percentage of the cost of the security.
- Zero Net Present Value (Zero NPV)
- Zero net present value occurs when the present value of expected cash inflows equals the present value of outflows. In capital budgeting, a project with zero NPV neither adds nor reduces shareholder value but meets the required rate of return. It represents the break-even point in investment evaluation.
- Zero Growth Rate
- Zero growth rate refers to a financial scenario where revenue, earnings, or asset levels remain constant over time. In valuation models, assuming zero growth simplifies long-term projections and dividend discount calculations. Analysts use this assumption cautiously when forecasting mature businesses with stable but non-expanding operations.
- Zakat Accounting
- Zakat accounting involves calculating and recording obligatory charitable contributions required under Islamic finance principles. Businesses determine zakat based on qualifying assets, liabilities, and net wealth thresholds. Proper accounting ensures compliance with religious and regulatory requirements, especially in jurisdictions where zakat reporting is formally integrated into financial oversight systems.
- Zero Defect Accounting
- Zero defect accounting applies quality management principles to financial reporting, aiming for error-free entries and reconciliation. It focuses on preventive controls, accuracy, and continuous improvement to ensure financial data integrity and compliance with auditing standards.
- Zonal Costing
- Zonal costing involves calculating and comparing costs incurred across different operational zones or branches of a company. It assists management in evaluating regional profitability, optimising logistics, and implementing cost-control strategies tailored to each zone.
- Z-Trend Analysis
- Z-trend analysis uses statistical standardisation (z-scores) to identify deviations from normal performance in financial data. It helps accountants and auditors detect anomalies, such as unusual transactions or outlier trends, supporting fraud detection and financial risk assessment.
- Zero Variance
Zero variance occurs when actual financial outcomes perfectly match budgeted or standard figures. While rare in practice, it signifies accurate forecasting and operational control. Analysts use variance measurement to assess performance consistency and the precision of planning assumptions.
- Zonal Reporting
- Zonal reporting is a management accounting technique that organises financial data based on geographical or operational zones. It helps multinational or multi-branch organisations assess regional performance, allocate resources effectively, and identify profitable or underperforming areas.
- Zero-Sum Game
- A zero-sum game describes a financial situation where one party’s gain equals another’s loss, keeping the total value constant. It is often used in trading, investment, or resource allocation analysis to assess competitive scenarios and strategic decision outcomes.
- Zone of Possible Agreement (ZOPA)
- In accounting and financial negotiations, the Zone of Possible Agreement represents the range within which two parties can find mutually acceptable terms. Understanding ZOPA aids in contract pricing, mergers, or financing negotiations by balancing risk and reward for both sides.
- Z-Score (Altman Z-Score)
- The Z-Score is a financial metric developed by Edward Altman to predict the likelihood of business bankruptcy. It combines profitability, leverage, liquidity, and solvency ratios into a single score. A low Z-Score indicates financial distress, while a higher score suggests stability.
- Zero Balance Account (ZBA)
- A zero balance account is a type of bank account used by businesses to optimise cash management. Funds are automatically transferred to or from a master account to maintain a zero balance. It helps centralise liquidity, prevent idle funds, and simplify daily reconciliation.
- Zero Inventory System
- A zero inventory system is a just-in-time inventory strategy where goods are ordered and produced only as needed. It reduces storage costs and waste but requires precise demand forecasting and supplier reliability. Accountants monitor it closely to track cost savings and manage risks.
- Zero-Coupon Bond
- A zero-coupon bond is a debt security that doesn’t pay periodic interest. Instead, it’s issued at a discount and matures at face value. The difference between the purchase price and maturity value represents the investor’s return. It’s often used for long-term planning in accounting and finance.
- Zero-Based Budgeting (ZBB)
- Zero-based budgeting is a method where every expense must be justified for each new period, starting from a zero base. Unlike traditional budgeting, it doesn’t carry forward previous budgets. ZBB helps eliminate unnecessary spending, but requires more time, detailed planning, and justification of all costs.
Call For More Info
+1 888 333 0992
Let’s Request a Schedule For Free Consultation
Team You Can Count On
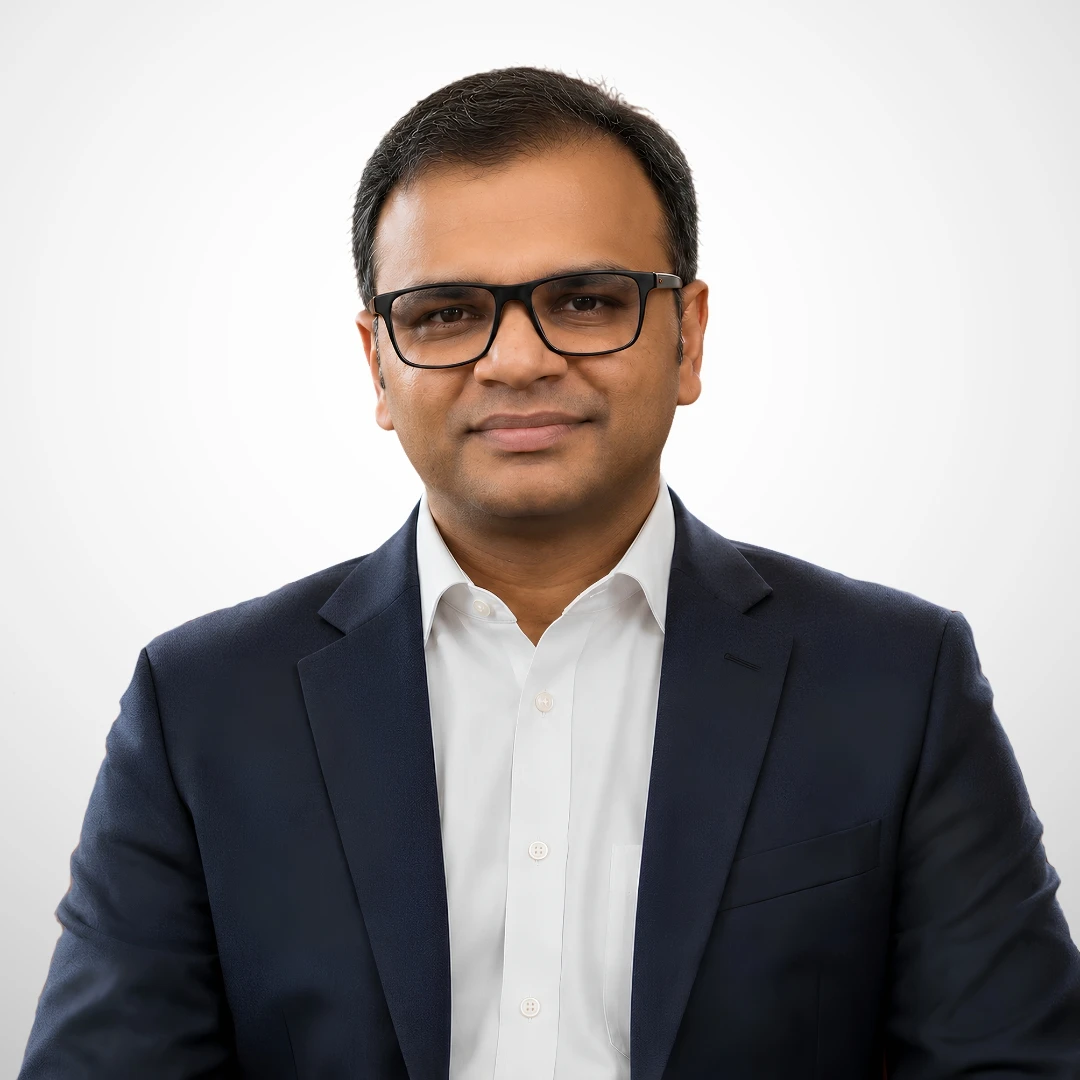
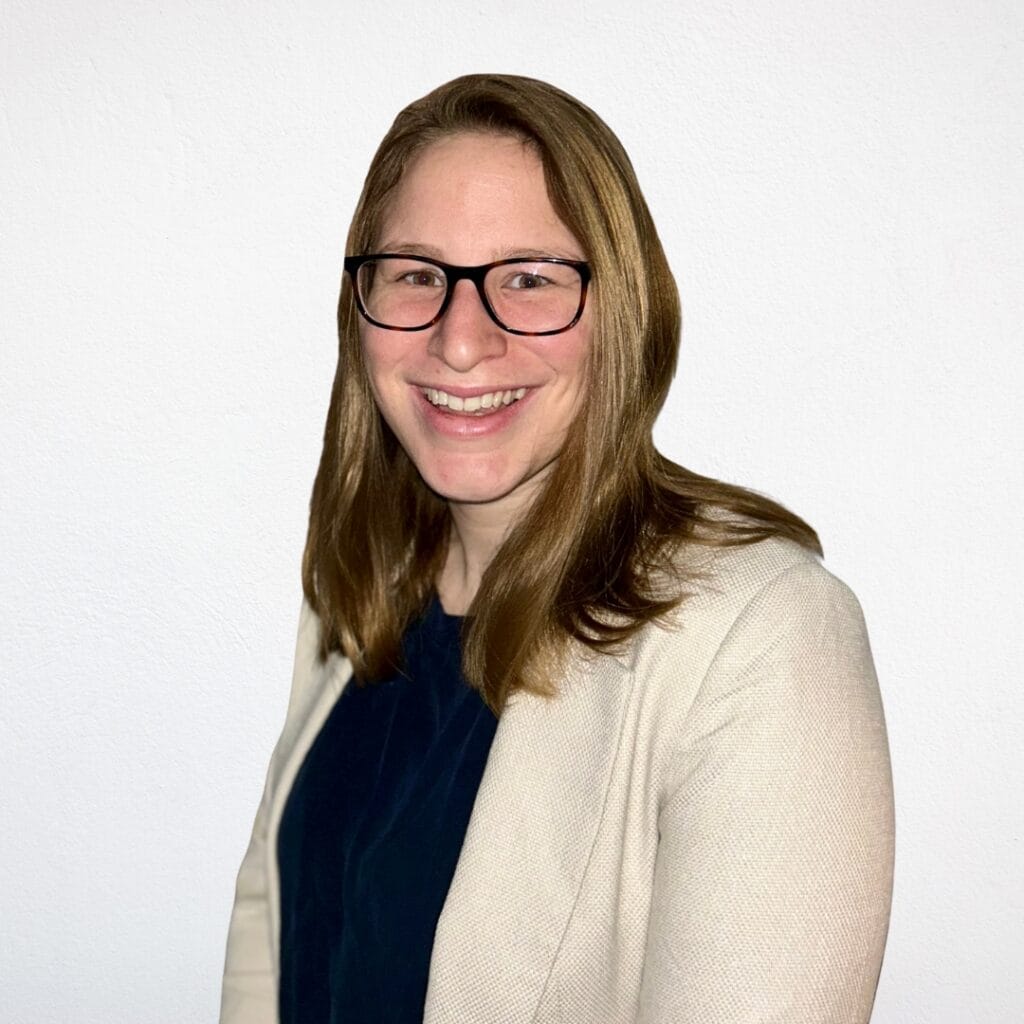
Allison Rinehimer
Operations Manager
Allison is a Certified Public Accountant (CPA) and a member of the AICPA. She oversees operations at Ledger Labs, ensuring accurate, compliant financials for hundreds of clients. With experience in both public and private accounting, she builds scalable systems that support fast-growing ecommerce businesses.
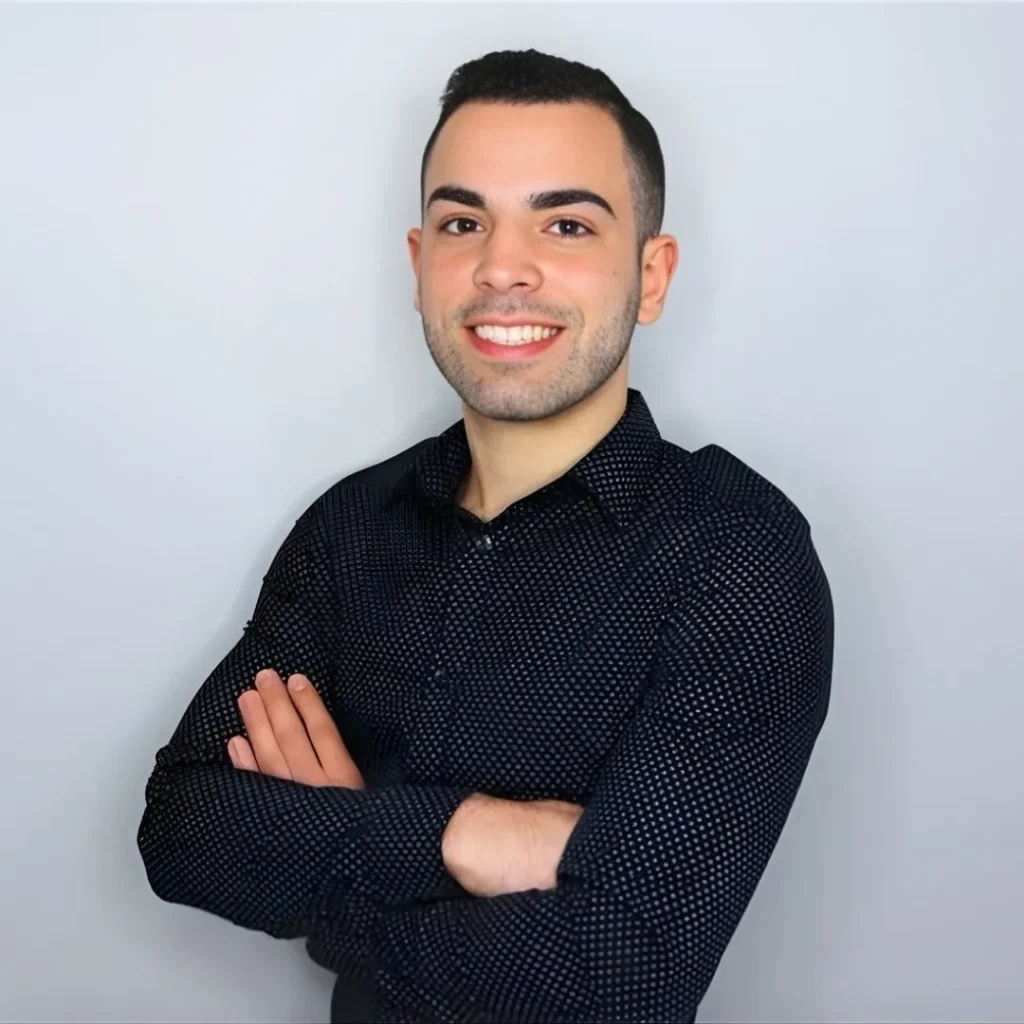
Matt Hidalgo
Accountant
Matt brings 7+ years of accounting experience across ecommerce, SaaS, and technology. He specializes in financial reporting, month-end close management, and ERP implementations (including NetSuite transitions). Matt ensures our clients get accurate, timely financials they can rely on for growth decisions.
Accounting Software We Work In


zoho inventory


Odoo


Shopify

Expert Accounting & Tax Insights.
Trusted by Leading Publications
Stay informed with expert viewpoints and industry trends shaping the future of finance and accounting

BUSINESS ACCOUNTING
How To Find A Small Business Accountant?
Learn when to hire an accountant, what questions to ask, and how expert financial guidance supports business growth.

AI & Tax Technology
What does an AI-driven IRS mean for small accounting firms?
Insights on how the IRS is using AI and What it means for compliance, efficiency, and the future of accounting firms.

Tax compliance
Unresolved Section 174A Questions After Rev. Proc. 2025-28
Key takeaways and open questions businesses should know.

accounting technology
Optimizing Accounting Workflows: How Modern Firms Save Time with ERP Systems
How ERP solutions streamline operations and drive efficiency.
Need a Finance Expert for Your Next Story?
Journalists, editors, bloggers, and content creators can rely on our accounting and finance professionals for expert quotes, commentary, and industry insights.
Top Notch Consulting
Get An Industry-Specific Custom Proposal And Consultation Now!
Book a free 30-minute consultation with Gary Jain, Co-founder of Ledger Labs, a seasoned accountant with 12+ years of experience helping small and mid-sized US businesses boost growth, streamline finances, and plan for the future.
Always Included:
- A birds-eye view of your company's financial health, processes, any points of concern and future growth plans.
- Services we can help you with
- A step-by-step roadmap with clear milestones tailored to your business goals.
- Estimated cost of our services, in case you ask for it.
Never Included:
- High-pressure sales
- Endless followups
- Generic finance-speak
Fill out the form and we’ll send you a link to schedule your free session.
Get Expert Insights
Start Your Free Business Audit
Our Testimonials
What Our Customers Say
Find out what our customers are saying about our products.
Since working with Ledger labs, our bookkeeping and Controller processes have been streamlined. The routine accounting tasks are managed on a predictable schedule, and checklists are used to ensure that all required documents are processed within the proper deadlines. We have improved the accuracy and timeliness of our financial statements and other crucial
Patrik Nichols CFOWe have a unique business, and almost all the accounting firms we have engaged so far have been unable to get a hold of our business. But Ledger Labs really took the bull by its horn. They understood our business better than us & created a very customized process & systems to streamline our accounting department. We now have detailed step-by-step process documentation, checklists & schedule of reports.
Amanda Fludd CEOLedger Labs found $18K in missed deductions that our old accountant completely missed, same books, same receipts, totally different results. That’s when I knew we were finally working with pros. Since then, they’ve helped us restructure expenses and make tax planning part of the daily flow, not just something we scramble on last minute.
Michael Smith CFOGary, yes. The founder, took the time to really understand our business and where we were struggling. Within a few weeks, our books were clean, our cash flow was clear, and we were spending way less time managing it all. You can tell he genuinely cares, and that energy runs through the whole team
Nicole Allen Founder & CEO
News & Blogs
Our Thought Leadership
Our learnings from years of multidimensional experience have been summarized in these articles!
See What Happens When You Work With Us
From saving thousands to scaling fast, these stories highlight how we help businesses grow smarter with real financial strategy and execution.
Empowering Business Confidence Through Precision and Insight
Navigating Financial Complexity to Secure Investment


My main problem always has been to know my accurate profits & this is precisely what Ledger Labs helped me with. They went through my entire supply chain costs, my monthly operational expenses, and COGS and got me the correct costing of my goods and the cost of running the business. Now I know how much I need to sell & at what price I should sell it to be profitable.
Ariel Robinson CEO & Founder